What Is Wealth Building and How Does It Work?
Building wealth is not only about earning a high salary or becoming financially successful overnight.
Wealth building is the gradual process of increasing what you own, reducing what you owe, and allowing your money and assets to grow over time.
For most people, wealth is built through a combination of earning income, controlling expenses, saving regularly, investing in suitable assets, managing debt and staying consistent for many years.
This article explains what wealth building means, how it works, and the difference between income, savings, assets and net worth. It also shows how a person can start building wealth even without a very high income.
What Is Wealth Building?
Wealth building means creating and increasing your financial resources over time.
A simple way to understand it is:
Earn → Save → Invest → Grow → Protect → Repeat
Your income gives you money to work with. Saving creates a surplus. That surplus can be invested in assets that may grow in value or generate income. Over time, these assets can increase your net worth.
SEBI’s investor education resources similarly connect financial planning with saving, investing, goal setting, retirement planning, insurance and debt management.
Wealth building is therefore not one single investment. It is a long-term financial process.
Income, Savings, Assets and Net Worth: What Is the Difference?
These four terms are often used together, but they mean different things.
| Term | Simple Meaning | Example |
|---|---|---|
| Income | Money you earn | Salary of ₹1 lakh per month |
| Savings | Money left after expenses and set aside for future needs | ₹30,000 saved from monthly income |
| Assets | Things that have financial value | Bank deposits, mutual funds, gold, property |
| Net Worth | Total assets minus total liabilities | Assets of ₹50 lakh – loans of ₹20 lakh = ₹30 lakh |
Understanding these differences makes wealth building much easier.
What Is Income?
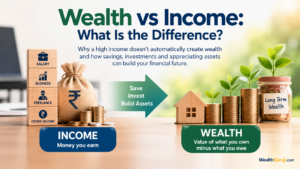
Income is the money you earn.
For an individual, income may come from:
- Salary
- Business income
- Professional fees
- Rental income
- Interest
- Dividends
- Other sources of regular earnings
For example, suppose your monthly salary is ₹1,00,000.
That ₹1,00,000 is your income. It does not automatically mean you are wealthy.
A person earning ₹1,00,000 may spend almost the full amount every month. Another person earning ₹70,000 may save and invest regularly.
The level of income matters because a higher income can create more room for saving and investing, but income alone is not the same as wealth.
What Are Savings?
Savings are the part of your income that you do not spend and keep aside for future needs.
SEBI explains saving simply as:
Saving = Income – Expenses
RBI’s financial awareness material also presents saving as income minus expenditure and highlights safety, liquidity and return as important considerations when deciding where to keep savings.
For example:
Monthly income: ₹1,00,000
Monthly expenses: ₹70,000
Monthly savings: ₹30,000
Savings are important because they can help you deal with emergencies, meet financial goals and create money that can eventually be invested.
However, simply keeping all your money as idle cash may not be enough for long-term wealth creation. The purpose and time horizon of the money matter.
What Are Assets?
An asset is something that has financial value.
Common examples include:
- Cash and bank balances
- Fixed deposits
- Mutual funds
- Stocks
- Bonds
- Gold
- Real estate
- Retirement savings
- Business ownership
Some assets may produce income. Others may increase in value over time. Some can do both.
For example:
A rental property may provide rent and may also increase in market value.
A mutual fund investment may grow in value.
A bank deposit may earn interest.
A business may generate profits and become more valuable.
This is why wealth building is closely connected with accumulating and growing assets.
At the same time, not every asset is equally suitable for every person. SEBI advises investors to consider goals, time horizon, risk tolerance, diversification, liquidity and tax implications before choosing investments.
What Is Net Worth?
Net worth gives you a snapshot of your overall financial position.
The basic formula is:
Net Worth = Total Assets – Total Liabilities
FINRA uses the same basic approach: add the value of what you own and subtract what you owe.
Simple Example
Suppose you have:
- Savings and bank deposits: ₹5 lakh
- Mutual funds and stocks: ₹10 lakh
- Gold: ₹5 lakh
- Property: ₹40 lakh
Total Assets = ₹60 lakh
Now suppose you have:
- Home loan outstanding: ₹20 lakh
- Personal loan: ₹3 lakh
Total Liabilities = ₹23 lakh
Therefore:
Net Worth = ₹60 lakh – ₹23 lakh = ₹37 lakh
Your net worth is ₹37 lakh.
This number is often much more useful for measuring long-term financial progress than simply looking at your monthly salary.
How Does Wealth Building Work?
Wealth building usually happens through several connected steps.
1. Increase Your Earning Capacity
The first step is creating income.
This can happen through:
- Improving professional skills
- Changing jobs when appropriate
- Building a business
- Developing additional income sources
- Increasing your value in the marketplace
The goal is not simply to earn more and spend more. The goal is to create a larger gap between income and expenses.
2. Spend Less Than You Earn
Wealth building becomes difficult when your lifestyle increases every time your income increases.
Suppose your income rises from ₹60,000 to ₹1,00,000 per month.
If your expenses also rise from ₹50,000 to ₹95,000, your financial surplus has increased only slightly.
Instead, try to increase savings as income grows.
For example:
Higher income → Controlled lifestyle increase → Higher savings → Higher investment
This creates a stronger foundation for long-term wealth creation.
3. Build an Emergency Fund
Before taking significant investment risk, it is useful to maintain money that can handle unexpected expenses.
An emergency fund can help with situations such as:
- Temporary loss of income
- Medical expenses
- Urgent repairs
- Unexpected family expenses
The CFPB describes emergency savings as money set aside specifically for unplanned expenses or financial emergencies.
FINRA notes that many financial planners use three to six months of living expenses as a general emergency-fund goal, although the right amount depends on the individual situation.
The important point is to keep emergency money accessible and separate from money meant for long-term investment.
4. Convert Savings Into Investments
Savings become more powerful for long-term wealth building when some of them are invested appropriately.
Depending on your financial goals, risk tolerance and time horizon, investment assets may include:
- Mutual funds
- Stocks
- Bonds
- Retirement savings
- Gold
- Real estate
- Other regulated investment products
Investment choices should be based on your financial situation rather than simply following what is popular.
SEBI specifically highlights the importance of understanding risk, investment horizon, diversification, liquidity and asset allocation before investing.
5. Give Your Money Time to Grow
One of the biggest advantages in wealth building is time.
When investment returns remain invested, future returns can be earned on a larger amount. This is the basic idea behind compounding. Investor.gov defines compound interest as interest earned on the original principal and accumulated interest.
For example, imagine investing ₹5,000 every month for many years.
The early years may not look very impressive.
But over a longer period, your total contributions and investment growth can become much larger.
This is why starting early and investing regularly can matter so much. Investor.gov and FINRA both emphasize regular contributions and the potential benefits of compounding over time.
The exact return is never guaranteed. Market-linked investments can rise and fall, and actual results depend on the investment, costs, taxes and market conditions. SEBI also cautions that investments involve risk and that past performance does not guarantee future returns.
Wealth Building Is a Long-Term Process
One common mistake is expecting wealth to grow quickly.
Real wealth building is usually much more boring than that.
You may:
Save ₹10,000 this month.
Then save another ₹10,000 next month.
You invest regularly.
You increase your investment when your income rises.
You reduce expensive debt.
You continue for 10, 15 or 20 years.
The individual actions may appear small, but their combined effect can become meaningful over a long period.
This is why consistency often matters more than trying to find a quick way to become rich.
A Simple Wealth-Building Example
Consider a person earning ₹80,000 per month.
Suppose the monthly plan looks like this:
| Financial Activity | Amount |
|---|---|
| Income | ₹80,000 |
| Monthly expenses | ₹55,000 |
| Savings | ₹25,000 |
| Long-term investment | ₹18,000 |
| Emergency/short-term savings | ₹7,000 |
The person’s income is ₹80,000.
But the more important long-term question is:
What happens to the ₹25,000 financial surplus every month?
Over time, that surplus may become:
- Emergency savings
- Retirement savings
- Mutual fund investments
- Gold investments
- Property-related capital
- Other financial assets
As assets increase and liabilities are managed, net worth can gradually rise.
That is wealth building in practical terms.
Assets Can Also Help Generate More Income
Wealth building becomes stronger when your assets can produce additional cash flow.
For example:
Salary → Savings → Investment → Asset → Additional income → Reinvestment
A rental property may generate rent.
A business may generate profits.
Certain investments may generate interest or dividends, depending on the investment.
The additional cash flow can then be saved or reinvested.
This creates the possibility of a cycle where money helps create more money.
Managing Debt Is Also Part of Wealth Building
It is easy to focus only on investments and ignore liabilities.
But debt directly affects net worth.
For example:
Assets = ₹50 lakh
Liabilities = ₹35 lakh
Net Worth = ₹15 lakh
If you reduce liabilities while keeping your asset position stable, your net worth improves.
High-interest debt deserves particular attention because interest costs can work against your financial goals. FINRA notes that paying down expensive debt can strengthen your financial foundation and improve cash flow.
Wealth building is therefore not just about buying assets.
It is also about managing liabilities intelligently.
Diversification Matters
Putting all your wealth into one asset can create concentration risk.
For example, a person who keeps almost all of their wealth in a single property, one stock or one business may face a larger financial impact if that asset performs poorly.
Diversification means spreading investments across different assets rather than depending too heavily on one.
SEBI notes that different asset classes can behave differently under changing economic conditions and that diversification can reduce the impact of poor performance in a single investment.
Diversification does not guarantee profits or eliminate risk. It is simply one way of managing investment risk.
How to Start Building Wealth From Today
You do not need to wait until your income becomes very high.
Start with the basics.
Step 1: Know Your Numbers
Write down:
- Monthly income
- Monthly expenses
- Total savings
- Investments
- Loans
- Other liabilities
This gives you a starting point.
Step 2: Calculate Your Net Worth
Use:
Assets – Liabilities = Net Worth
Review it periodically to see whether your financial position is improving.
Step 3: Create an Emergency Fund
Keep money aside for genuine unexpected expenses.
Step 4: Start Investing Regularly
Choose investments based on your goals, risk capacity and time horizon.
Step 5: Increase Investments With Income
When your salary or business income rises, try to increase your investment amount instead of allowing every increase to become lifestyle spending.
Step 6: Avoid Unnecessary High-Cost Debt
Reducing expensive debt can improve your ability to save and invest.
Step 7: Stay Consistent
Wealth building is a long journey.
A simple strategy followed for many years can be more useful than constantly changing strategies in search of quick returns.
Wealth Building Is Not the Same as Looking Rich
A large house, expensive car or high salary may make someone appear financially successful.
But these things do not tell the complete financial story.
A better question is:
How much do you own, how much do you owe, and how much of your income is helping build future financial security?
Someone with a moderate income and strong financial habits may gradually build significant assets.
Another person with a high income may build little wealth if most of the income is spent.
That is why wealth is about building financial strength over time, not simply displaying a high standard of living.
Key Takeaways
- Income is the money you earn.
- Savings are the money you set aside after expenses.
- Assets are things that have financial value.
- Liabilities are amounts you owe.
- Net worth is assets minus liabilities.
- Wealth building is a long-term process, not a quick-money strategy.
- Saving creates the surplus that can later be invested.
- Investing can help assets grow or generate income, but returns are not guaranteed.
- Time, consistency and compounding can play an important role in long-term wealth creation.
- Managing debt and maintaining an emergency fund are also important parts of a strong financial foundation.
Conclusion
Wealth building is the gradual process of turning income into lasting financial assets and increasing net worth over time.
It starts with earning money, but it does not end there.
The real process is:
Earn → Save → Invest → Grow → Manage Debt → Protect → Repeat
You do not need to become rich before you start building wealth. In many cases, the habits you develop with the money you have today are what help create wealth in the future.
Start by understanding your income, expenses, savings, assets and liabilities. Then build a financial plan that you can follow consistently.
Over the years, small financial decisions can add up to a much stronger financial position.
Frequently Asked Questions About Wealth Building
What is wealth building in simple words?
Wealth building means gradually increasing your assets, reducing unnecessary debt and growing your net worth over time through saving, investing and sound financial management.
Is income the same as wealth?
No. Income is the money you earn, while wealth is generally measured by the value of your assets after subtracting your liabilities.
What is the difference between savings and assets?
Savings are money set aside for future use. Once savings are held in forms such as bank deposits, they can be counted among your financial assets. Assets can also include investments, property, gold and business ownership.
How is net worth calculated?
The formula is:
Net Worth = Total Assets – Total Liabilities
For example, if you own ₹40 lakh of assets and owe ₹15 lakh, your net worth is ₹25 lakh.
Can a person build wealth with a normal salary?
Yes. Wealth building does not require an exceptionally high income. Consistent saving, suitable investing, controlled spending and responsible debt management can help improve net worth over time.
How long does it take to build wealth?
There is no fixed timeline. It depends on income, savings rate, investment returns, debt, expenses, financial goals and the number of years you remain consistent.
Why is starting early important for wealth building?
Starting early gives your savings and investments more time to potentially grow and benefit from compounding. The earlier you begin, the longer your money has to work toward your financial goals.
Is investing necessary for wealth building?
Investing is an important part of many long-term wealth-building plans, but the right investment depends on the person’s goals, risk tolerance, time horizon and financial circumstances. Investments also carry risk, and returns are not guaranteed.