Buy and Hold Residential Property: A Simple Real Estate Wealth-Building Strategy
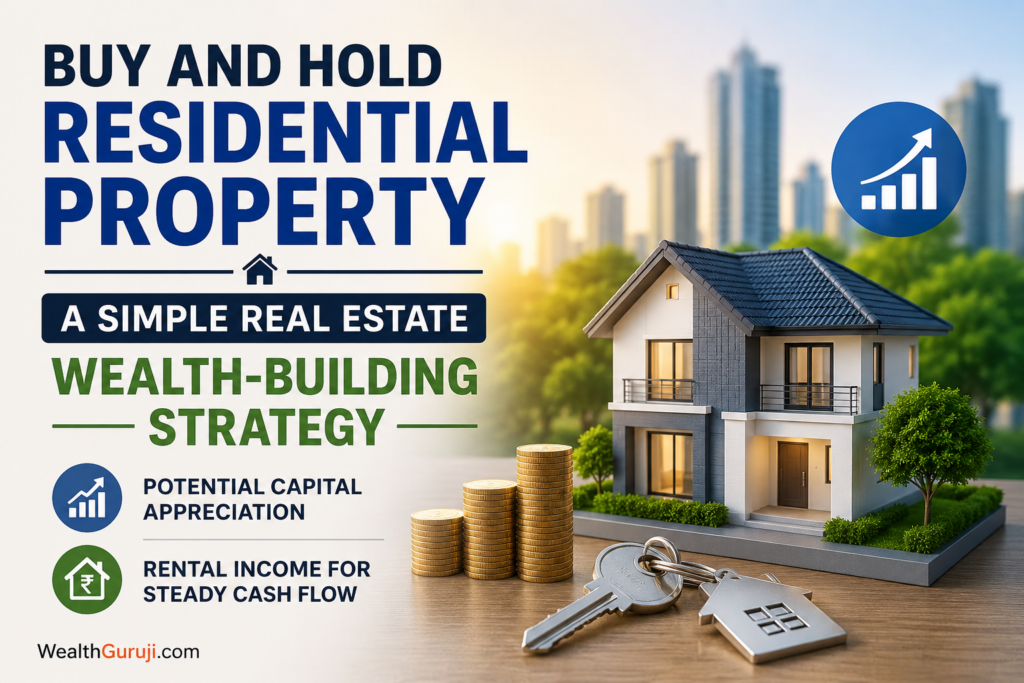
Build long-term wealth by choosing the right property, generating rental income, and giving your investment time to grow.
Introduction
Real estate can be an important part of a long-term wealth-building plan. One of the simplest strategies many property investors follow is buy and hold residential property.
The idea is simple.
Buy a good residential property → Hold it for the long term → Earn rental income → Benefit from potential property appreciation.
This strategy is not about making quick money. It is about buying carefully, managing the property properly, and giving your investment enough time.
In this article, we will understand how the buy-and-hold real estate strategy works, what to look for before buying a property, and the common mistakes investors should avoid.
What Is a Buy and Hold Residential Property Strategy?
Buy and hold means purchasing a residential property and keeping it for a long period instead of selling it after a short-term price increase.
For example, suppose you buy a 2 BHK apartment for ₹50 lakh in an area that is still developing.
Over the next 10 years, the area may see:
- Better roads
- New offices and business centres
- Improved public transport
- Schools and hospitals
- Shopping and other facilities
- More people moving into the area
As the area develops, demand for homes may increase. This can support the property’s value and rental demand.
If the property is rented, you can also receive monthly rental income while continuing to own the property.
This is the basic idea behind buy-and-hold real estate investing.
How Does Buy and Hold Real Estate Build Wealth?
A residential property can potentially create wealth in two main ways.
1. Capital Appreciation
Capital appreciation means an increase in the market value of your property over time.
For example, if you buy a property for ₹50 lakh and its value increases to ₹80 lakh after several years, the property has appreciated by ₹30 lakh.
Property appreciation depends on many factors.
These can include:
- Location
- Infrastructure
- Employment opportunities
- Demand and supply
- Connectivity
- Population growth
- Economic conditions
There is no guarantee that a property will appreciate at a particular rate.
This is why buying the right property is more important than simply buying any property and waiting.
2. Rental Income
A residential property can also generate rental income.
Suppose you buy a property for ₹50 lakh and rent it for ₹20,000 per month.
Your annual rent would be:
₹20,000 × 12 = ₹2.40 lakh
The simple gross rental yield would be:
₹2.40 lakh ÷ ₹50 lakh × 100 = 4.8%
This is only a basic calculation.
Your actual return can be lower after considering:
- Maintenance
- Repairs
- Vacancy periods
- Property taxes
- Society charges
- Brokerage
- Other property expenses
Still, rental income can provide regular cash flow and help cover some of the costs of owning the property.
Why Location Matters in Real Estate Investment
When buying residential property for the long term, location should be one of your biggest considerations.
A property may look attractive, but if the location has weak demand, its rental and resale potential may also be limited.
On the other hand, a property in a well-connected and growing location may have better long-term potential.
Factors to Consider When Selecting a Location
Look for:
- Good road connectivity
- Public transport
- Employment opportunities
- IT parks and business hubs
- Schools and colleges
- Hospitals
- Shopping facilities
- Upcoming infrastructure
- Population growth
- Rental demand
- Future development
Do not select a location only because someone says that property prices will increase in the future.
Try to understand why people will want to live there in the future.
That is a much better way to evaluate a real estate investment.
How to Identify a Growing Location
A growing location usually has a combination of economic and infrastructure development.
Employment Growth
People need homes close to their workplaces.
New offices, IT parks, industrial areas and business centres can increase demand for nearby housing.
Infrastructure Development
New roads, metro routes, highways and other transport facilities can improve connectivity.
Better connectivity can make an area more convenient for residents.
Social Infrastructure
Families usually want access to schools, hospitals, markets and other daily-use facilities.
An area that is developing these facilities may become more attractive over time.
Rental Demand
If people are already looking for rental homes in an area, it can be a positive sign for a buy-and-hold investor.
Check actual rents for similar properties instead of relying only on advertisements or assumptions.
Future Property Supply
Look at how many new projects are coming up around your preferred location.
If a large number of similar apartments are being launched, future rental competition may increase.
How to Choose the Right Residential Property
Once you identify a good location, the next step is selecting the right property.
Do not focus only on the building’s appearance or amenities.
Consider practical factors such as:
- Purchase price
- Carpet area
- Floor plan
- Construction quality
- Parking
- Maintenance charges
- Property age
- Water supply
- Electricity supply
- Connectivity
- Rental demand
- Resale demand
- Builder or seller reputation
- Property documents
A property that is easy to rent and has good resale demand can be more useful for a long-term investor.
You should also compare similar properties in the same area before making a decision.
New Property or Resale Property?
Both new and resale properties can work for a buy-and-hold strategy.
| Factor | New Property | Resale Property |
| Property condition | New construction | Existing property |
| Amenities | Usually modern | Depends on project |
| Repairs | Usually lower initially | May require repairs |
| Rental income | May start after possession | Can often start sooner |
| Inspection | Limited before possession in some cases | Actual property can be inspected |
| Price negotiation | Depends on project | May offer more flexibility |
A new property may offer modern construction and amenities. However, if it is under construction, you may have to wait for possession before renting it out.
A resale property can allow you to inspect the actual building, surrounding area and neighbourhood.
The right choice depends on your budget, investment goal, location, property price and expected rental demand.
Can a Home Loan Be Used for Buy and Hold?
Many investors use home loans to purchase residential property.
A home loan allows you to buy a property without paying the entire purchase price from your savings.
However, borrowing needs to be planned carefully.
Before Taking a Home Loan, Calculate:
- Down payment
- Monthly EMI
- Interest cost
- Loan tenure
- Expected rent
- Maintenance expenses
- Property taxes
- Emergency fund
- Other monthly financial commitments
Do not assume that rent will always cover your EMI.
A property can remain vacant for some time. Tenants can change. Repairs can also result in unexpected expenses.
A good approach is to make sure you can comfortably manage the property even if rental income is temporarily lower than expected.
Understanding Rental Yield
Rental yield is an important number for property investors.
Rental Yield Formula
Rental Yield = Annual Rental Income ÷ Property Value × 100
For example:
Property price: ₹60 lakh
Monthly rent: ₹22,000
Annual rent:
₹22,000 × 12 = ₹2.64 lakh
Gross rental yield:
₹2.64 lakh ÷ ₹60 lakh × 100 = 4.4%
This calculation gives you a starting point.
For a more realistic picture, also consider:
- Maintenance
- Repairs
- Vacancy
- Property tax
- Society charges
- Brokerage
- Loan interest
A property with a good rental yield is not automatically a good investment.
Location, property quality, purchase price and future demand still matter.
Why Long-Term Holding Can Be Powerful
Real estate markets do not move in a straight line.
There can be periods when property prices rise quickly. There can also be periods when prices remain stable or grow slowly.
A long-term investor does not need to make decisions based on every short-term price movement.
If the property has good fundamentals, holding it for several years can give the location time to develop.
During the holding period:
- The property may appreciate
- Rent may increase
- The loan balance may reduce
- Your ownership equity may increase
- The surrounding area may become more developed
This is why patience is an important part of a buy-and-hold real estate strategy.
A Simple Example of Long-Term Property Growth
Let us take a simple example.
Suppose you purchase a residential property for ₹50 lakh.
For illustration, assume the property grows at an average rate of 7% per year.
The approximate value would be:
| Holding Period | Illustrative Value |
| 5 years | ₹70 lakh |
| 10 years | ₹98 lakh |
| 15 years | ₹1.38 crore |
| 20 years | ₹1.94 crore |
Important Note
These numbers are only an illustration of mathematical compounding.
Actual property prices do not increase by the same percentage every year.
They can rise faster, grow slowly, remain unchanged or fall depending on market conditions.
Never buy a property based on an assumption that it will deliver a fixed annual return.
Buy and Hold vs Short-Term Property Investment
Buy-and-hold investing is different from short-term property trading.
A short-term investor may buy a property with the intention of selling it after a relatively short period.
A buy-and-hold investor generally focuses on long-term ownership.
| Factor | Buy and Hold | Short-Term Trading |
| Investment period | Long term | Short term |
| Main focus | Wealth creation | Capital gain |
| Rental income | Important | Usually less important |
| Market timing | Less important | More important |
| Transaction costs | Less frequent | More frequent |
| Patience | Very important | Less important |
For people who do not want to frequently buy and sell properties, the buy-and-hold approach can be easier to manage.
Common Mistakes to Avoid
Buying a property for the long term does not automatically make it a good investment.
Here are some common mistakes to avoid.
Buying Only Because the Property Is Cheap
A cheap property in a weak location can remain a poor investment for many years.
Always understand why the property is cheaper than similar properties.
Ignoring Rental Demand
If there are very few tenants in the area, your expected rental income may not materialise.
Check actual rental demand before buying.
Taking a Loan That Is Too Large
A high EMI can put pressure on your monthly cash flow.
Make sure you can manage the loan even during difficult periods.
Expecting Property Prices to Double Quickly
Real estate appreciation varies from location to location.
Avoid investment decisions based on promises of guaranteed returns.
Ignoring Maintenance Costs
Property ownership involves ongoing expenses.
Budget for repairs, maintenance, society charges and other costs.
Buying Based Only on Future Infrastructure
An upcoming road, metro station or business hub may sound attractive.
However, check the actual status of the project, approvals and expected completion timeline before paying a premium.
Ignoring Legal Verification
Always check the property’s ownership and legal documents before purchasing.
Depending on the property, this may include title documents, approvals, encumbrance details, RERA information where applicable and other relevant records.
Professional legal advice can be useful, particularly for higher-value property purchases.
How to Build a Real Estate Property Portfolio
Investors who successfully manage one property may eventually consider buying additional properties.
But there is no need to rush.
A disciplined approach could be:
Step 1: Buy a property with strong fundamentals.
Step 2: Keep enough emergency savings.
Step 3: Manage the EMI and property expenses.
Step 4: Monitor rent and property performance.
Step 5: Build savings and equity over time.
Step 6: Consider another property only when your finances can comfortably support it.
The goal should not be to own the maximum number of properties.
The goal should be to own good-quality assets with manageable debt and sustainable cash flow.
Tax and Legal Considerations
Property investment also involves taxes, duties and legal responsibilities.
Depending on your situation, you may need to consider:
- Stamp duty
- Registration charges
- Property tax
- Tax on rental income
- Home loan tax benefits
- Capital gains tax
- Maintenance expenses
- Legal and documentation costs
Tax laws can change over time.
Always check the latest applicable rules and speak with a qualified tax professional when required.
When Buy and Hold May Not Be Suitable
Buy-and-hold is not the right strategy for every property or every investor.
Think carefully before investing if:
- The location has weak demand
- Rental demand is very low
- The property is significantly overpriced
- The EMI is difficult to manage
- The property has legal issues
- Maintenance costs are unusually high
- There is excessive housing supply
- You may need to sell the property soon
- Most of your wealth would be concentrated in one property
A long holding period cannot turn a fundamentally poor property into a good investment.
Buy and Hold Property Investment Checklist
Before buying a residential property for long-term investment, ask yourself:
☐ Is the location growing?
☐ Is there strong rental demand?
☐ Are employment opportunities available nearby?
☐ Is connectivity good or improving?
☐ Is the property reasonably priced?
☐ Have I compared similar properties?
☐ Can I comfortably afford the home loan?
☐ Do I have an emergency fund?
☐ Have I checked the property documents?
☐ Have I calculated realistic rental income?
☐ Have I considered maintenance and vacancy?
☐ Does the property have good resale potential?
☐ Can I comfortably hold the property for several years?
If you cannot answer these questions confidently, take more time to research before making the purchase.
Final Thoughts
Buy and hold residential property is a simple real estate wealth-building strategy, but choosing the right property is the key.
The strategy is not simply about buying a house and waiting for its price to increase.
It is about buying in a location where there is a reasonable basis for future demand, choosing a property that people want to live in, managing your loan and expenses carefully, and holding the asset for the long term.
Rental income can provide regular cash flow, while property appreciation may increase the value of your investment over time.
There will always be market ups and downs. Property prices may not rise every year, and rental income is never guaranteed.
But with proper research, sensible financing and patience, residential real estate can become an important part of a long-term wealth-building plan.
Buy carefully. Choose the location wisely. Manage your finances. Hold patiently.
Frequently Asked Questions
1. What is buy and hold in real estate?
Buy and hold is a long-term real estate investment strategy where you purchase a property and keep it for several years.
The objective is generally to benefit from potential capital appreciation and rental income.
2. Is buy and hold residential property a good investment?
It can be a useful long-term investment strategy when the property has good fundamentals, the location has sustainable demand and the investment is affordable.
However, property returns are not guaranteed.
3. How does residential property generate wealth?
Residential property can potentially generate wealth through two main sources:
- Capital appreciation
- Rental income
Loan repayment can also gradually increase the owner’s equity in the property.
4. How important is location when buying property?
Location is extremely important.
Employment opportunities, connectivity, infrastructure, schools, hospitals, rental demand and future development can influence the long-term demand for residential property.
5. How long should I hold a residential property?
There is no fixed holding period.
Buy-and-hold investors generally think in terms of many years rather than a few months.
The appropriate period depends on your financial goals, property and market conditions.
6. Can I buy residential property using a home loan?
Yes, eligible buyers can use home loans to purchase residential property.
However, the loan should be affordable, and you should have enough financial reserves to manage periods of vacancy or unexpected expenses.
7. What is rental yield?
Rental yield is a measure of the rental income generated by a property compared with its value.
The basic formula is:
Annual Rent ÷ Property Value × 100
Investors should also consider property expenses to understand the actual return.
8. Should I buy a new property or resale property?
Both can work.
A new property may offer modern construction and amenities, while a resale property allows you to inspect the existing building and may provide an opportunity to start earning rent sooner.
9. Is property appreciation guaranteed?
No.
Property prices can increase, remain stable or decline.
Performance depends on the location, property, demand, supply and wider economic conditions.
10. What is the biggest mistake in buy-and-hold property investment?
One of the biggest mistakes is buying a property without properly researching the location, price, rental demand, legal documents and financing.
A long holding period does not remove the risks of making a poor purchase.
11. Can rental income cover my home loan EMI?
It can cover part or, in some cases, a large portion of the EMI, but this should not be assumed.
Vacancy, maintenance, taxes and other expenses can reduce the actual rental cash flow.
12. Is buy and hold better than short-term property investment?
Neither strategy is automatically better.
Buy and hold focuses on long-term ownership, rental income and potential appreciation, while short-term investing focuses more on market timing and selling for a profit.
The appropriate strategy depends on the investor’s goals, finances and risk tolerance.