How to Calculate Your Net Worth: A Simple Guide With Example
Your income tells you how much you earn. Your net worth tells you how much you have actually built.
A person earning ₹2 lakh a month may have a lower net worth than someone earning ₹1 lakh if the first person has more debt and fewer assets. That is why income alone does not show your complete financial position.
The basic formula is simple:
Net Worth = Total Assets – Total Liabilities
This guide explains how to calculate net worth, what to include, a practical Indian example, and why tracking it can help you build long-term wealth.
What Is Net Worth?
Net worth is the value of everything you own after subtracting everything you owe.
In simple terms:
What You Own – What You Owe = Net Worth
Your net worth can be:
- Positive when assets are greater than liabilities
- Zero when both are equal
- Negative when liabilities are greater than assets
For example, if your assets are worth ₹60 lakh and your total liabilities are ₹20 lakh:
₹60 lakh – ₹20 lakh = ₹40 lakh net worth
SEBI and Investor.gov both use the assets-minus-liabilities approach for calculating net worth and tracking financial progress.
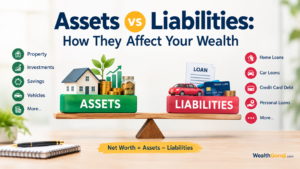
What Are Assets?
Assets are things you own that have financial value.
Common examples include:
- Bank savings
- Fixed deposits
- Mutual funds and shares
- EPF, PPF and NPS
- Gold
- Residential or commercial property
- Vehicles
- Business interests
When calculating net worth, use reasonable current values rather than automatically using the original purchase price.
For example, a property bought for ₹45 lakh several years ago may currently be worth ₹60 lakh. A realistic current value is more useful for a personal net-worth statement.
SEBI’s net-worth calculator includes savings, fixed deposits, mutual funds, EPF, PPF, NPS, shares, bonds and gold among assets.
What Are Liabilities?
Liabilities are amounts you owe to others.
Typical liabilities include:
- Home loan outstanding
- Car loan
- Personal loan
- Education loan
- Credit-card dues
- Business loans
- Other outstanding debt
Use the current outstanding balance, not the original loan amount.
For example, if you borrowed ₹50 lakh for a home and now owe ₹35 lakh, the liability is ₹35 lakh.
How to Calculate Your Net Worth
Step 1: List Your Assets
Write down the current value of your savings, investments, property, retirement funds, gold, vehicles and other valuable assets.
Step 2: List Your Liabilities
Record your outstanding home loans, personal loans, car loans, credit-card balances and other debt.
Step 3: Add Your Assets
Suppose your total assets are:
₹50 lakh
Step 4: Add Your Liabilities
Suppose your total liabilities are:
₹15 lakh
Step 5: Apply the Formula
Net Worth = ₹50 lakh – ₹15 lakh
Net Worth = ₹35 lakh
That ₹35 lakh is your estimated net worth based on the figures used.
Practical Net Worth Example
Consider an Indian household with the following assets:
| Assets | Value |
|---|---|
| Bank savings | ₹3 lakh |
| Mutual funds | ₹4 lakh |
| EPF/PPF | ₹2 lakh |
| Gold | ₹1 lakh |
| Residential property | ₹40 lakh |
| Total Assets | ₹50 lakh |
Liabilities:
| Liabilities | Outstanding |
|---|---|
| Home loan | ₹10 lakh |
| Car loan | ₹3 lakh |
| Personal loan | ₹1.5 lakh |
| Credit-card dues | ₹0.5 lakh |
| Total Liabilities | ₹15 lakh |
Therefore:
₹50 lakh – ₹15 lakh = ₹35 lakh
The household’s estimated net worth is ₹35 lakh.
Should Your Home and Car Be Included?
Home
Yes. Include your home at a reasonable current value and separately include the outstanding home loan as a liability.
For example:
Home value: ₹70 lakh
Home loan outstanding: ₹45 lakh
The net contribution from the property is approximately ₹25 lakh, before considering other assets and liabilities.
WealthGuruji’s article on financial wealth-building strategies explains how property, savings, investments and debt work together in wealth creation.
Car
A car can also be included, but use a realistic current resale value.
A vehicle purchased for ₹10 lakh several years ago may now be worth ₹5 lakh. Using ₹10 lakh would overstate your current net worth.
What If Your Net Worth Is Negative?
A negative net worth means your liabilities are greater than your assets.
For example:
Assets: ₹8 lakh
Liabilities: ₹12 lakh
Net worth: –₹4 lakh
This can happen when someone has large education, home or personal loans and has not yet accumulated many assets.
The important point is to monitor the trend and work on improving your financial position over time. Investor.gov notes that a negative net worth does not mean you should abandon your financial plan.
How Often Should You Track Net Worth?
For most people, checking net worth once or twice a year is enough. An annual review is especially useful for comparing your financial position from one year to the next.
For example:
| Year | Net Worth |
|---|---|
| March 2024 | ₹18 lakh |
| March 2025 | ₹24 lakh |
| March 2026 | ₹31 lakh |
This gives you a clearer picture of your financial progress than looking only at your salary.
How to Increase Your Net Worth
There are two basic ways to improve net worth:
Increase your assets and reduce your liabilities.
Practical steps include:
Save and invest regularly
Move a portion of your income into investments and long-term savings.
Reduce expensive debt
Paying down high-cost debt can improve your financial position.
Avoid unnecessary borrowing
Every new loan creates a liability that affects your net worth.
Build productive assets
Investments, property and other assets that can grow in value may contribute to long-term wealth creation.
You can also read WealthGuruji’s guide to long-term investing and its article on building wealth with physical gold.
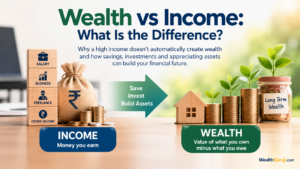
Net Worth vs Income
Income and net worth are not the same.
Income is the money you earn.
Net worth is what you own after subtracting what you owe.
For example:
Monthly income: ₹1,00,000
Net worth: ₹35,00,000
A high income can help you build wealth, but only if part of that income becomes savings, investments and other assets while debt remains manageable.
Common Mistakes When Calculating Net Worth
Using original purchase prices
Use current reasonable values instead.
Forgetting liabilities
Include credit-card balances, personal loans and other outstanding debt.
Counting property but not the loan
A ₹70 lakh home with a ₹45 lakh loan cannot be treated as ₹70 lakh of debt-free wealth.
Double-counting investments
Make sure the same investment is not included twice.
Key Takeaways
- Net Worth = Total Assets – Total Liabilities
- Include savings, investments, property, retirement funds, gold and other valuable assets.
- Subtract outstanding loans and other liabilities.
- Use current reasonable asset values.
- Review your net worth regularly to track financial progress.
- Focus on gradually increasing assets while managing debt.
Conclusion
Calculating your net worth is one of the simplest ways to understand your overall financial position.
Make two lists: what you own and what you owe. Add your assets, add your liabilities, and subtract liabilities from assets.
Assets – Liabilities = Net Worth
Tracking this number over time can help you see whether your savings and investments are growing, your debt is reducing and your financial position is improving.
The goal is not simply to have a bigger number. It is to build a stronger financial foundation for the future.
Frequently Asked Questions About Net Worth
What is the formula for calculating net worth?
Net Worth = Total Assets – Total Liabilities
What should I include in my net worth?
Include bank balances, fixed deposits, investments, retirement savings, property, gold, vehicles, business interests and other assets with financial value. Subtract outstanding debt.
Should I include my home loan?
Yes. Include the current property value as an asset and the outstanding home-loan balance as a liability.
Is EPF included in net worth?
Yes. EPF is a financial asset and can be included when calculating net worth.
Should gold jewellery be included?
Yes, where it has meaningful financial value. Use a realistic current value rather than the original purchase price.
How often should I calculate net worth?
For most people, an annual review is sufficient. A quarterly review can also be useful for active financial planning.
What does negative net worth mean?
It means your liabilities are greater than your assets. It can improve over time as you build assets and reduce debt.
Is net worth more important than income?
They measure different things. Income measures earnings, while net worth measures your accumulated financial position after liabilities.