How to Increase Your Net Worth Every Year: 7 Practical Strategies
Building wealth is not only about earning a higher salary. What matters is how much of your income you keep, how you invest it, how quickly you reduce debt, and how your assets grow over time.
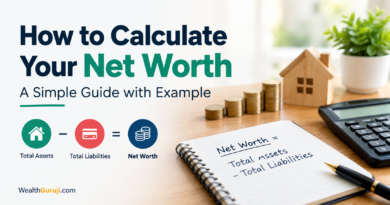
Your net worth gives you a simple way to measure this progress:
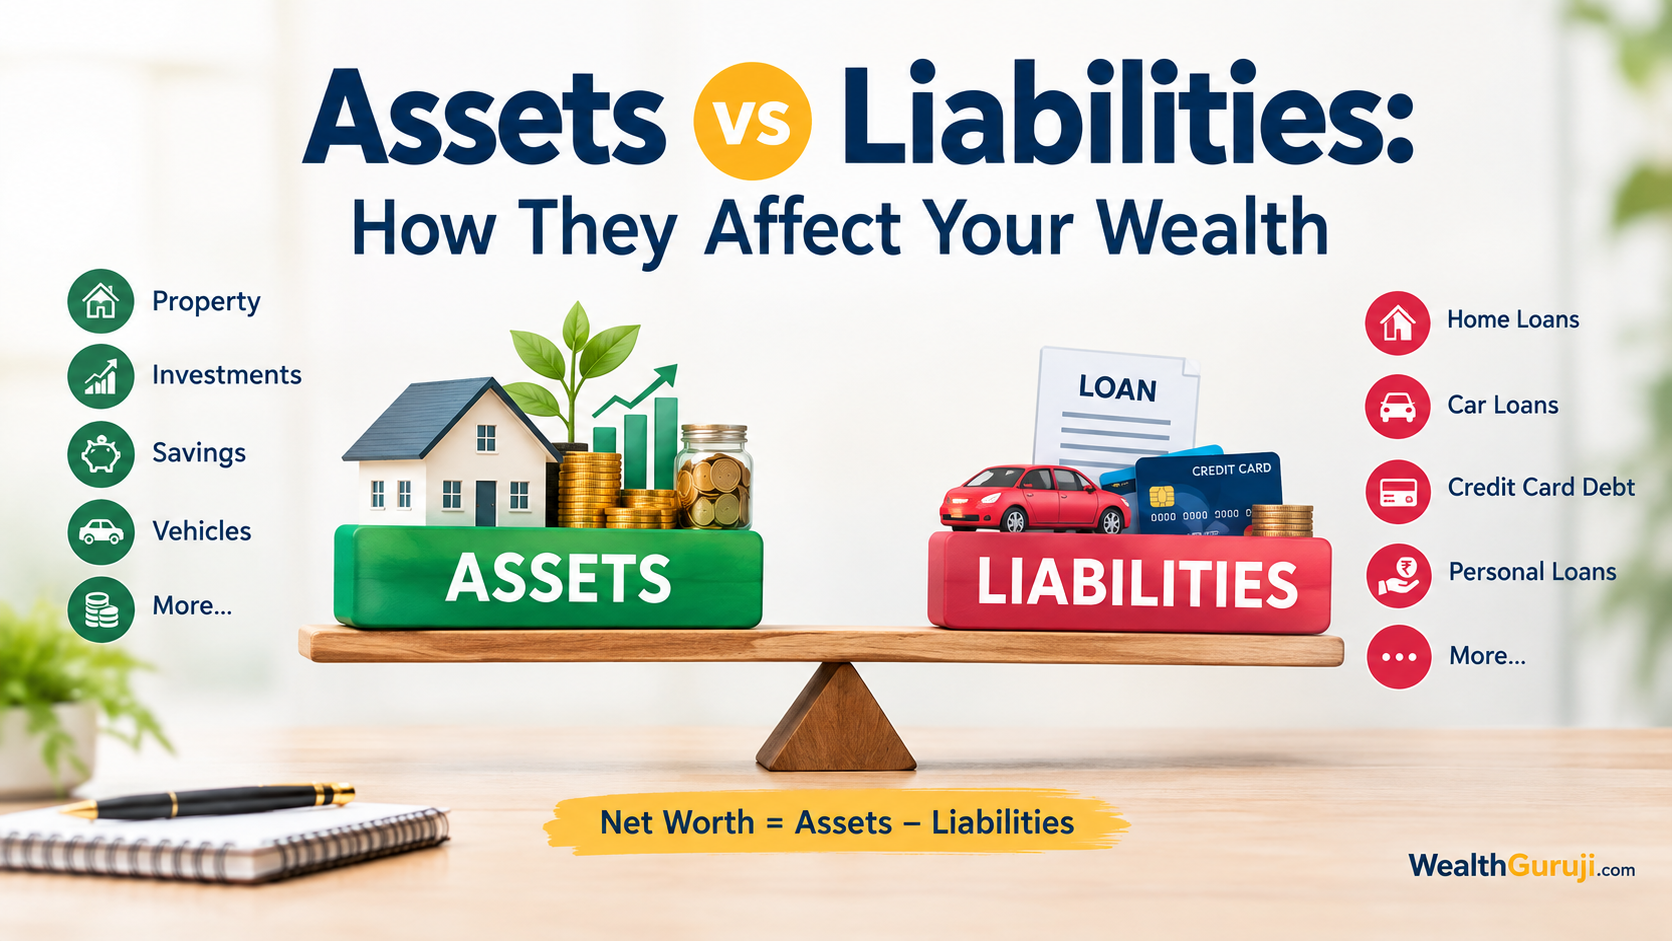
Net Worth = Total Assets − Total Liabilities
For example, if your savings, investments, property and other assets are worth ₹50 lakh and your total loans and other debts are ₹20 lakh, your net worth is ₹30 lakh.
The good news is that increasing net worth does not require one big financial decision. It usually comes from a series of small improvements repeated every year.
What Does It Mean to Increase Your Net Worth?
Your net worth can increase in four main ways:
| Wealth-building action | How it helps |
|---|---|
| Save more money | Increases the assets you own |
| Invest regularly | Gives your savings the opportunity to grow |
| Reduce debt | Lowers your liabilities |
| Grow asset values | Increases the value of investments or property |
The strongest financial progress often happens when several of these work together.
For example, you may invest ₹5 lakh during a year, repay ₹2 lakh of loan principal, and see some of your investments increase in value. Your net worth can therefore rise much faster than your bank balance alone suggests.
For a broader roadmap, see our guide to Financial Wealth Building Strategy.
1. Increase Your Savings Rate Every Year
One of the simplest ways to increase net worth is to save more from your income.
You do not necessarily need to make a dramatic lifestyle change. Instead, try to increase your savings whenever your income rises.
For example:
- Starting salary: ₹60,000 per month
- Monthly savings: ₹10,000
- After a salary increase, monthly income rises to ₹70,000
- Increase savings to ₹13,000 instead of increasing spending by the entire ₹10,000
This creates a habit of allowing your savings rate to rise along with your income.
Budgeting can help because it gives you a clear picture of where your money is going and how much can realistically be saved. Regular automatic transfers can also make saving more consistent.
Focus on the savings rate, not only the amount
Someone earning ₹1 lakh per month and saving ₹20,000 is saving 20% of income.
If that person later earns ₹1.3 lakh and saves ₹35,000, the improvement in the savings rate becomes an important driver of wealth creation.
A useful yearly question is:
“Can I save a little more this year than I did last year?”
2. Invest Your Savings Instead of Leaving Everything Idle
Saving creates surplus money. Investing gives that money a chance to grow.
Long-term investing can benefit from compounding, where returns earned on investments can themselves generate further returns over time.
For many investors, a disciplined approach is more practical than trying to predict the best time to enter or exit the market.
A SIP, for example, allows investors to invest a fixed amount at regular intervals in a mutual fund scheme. SEBI and AMFI provide investor education resources covering SIPs, mutual funds, diversification and investment risks.
The right investment depends on your:
- Financial goals
- Investment time horizon
- Risk tolerance
- Existing assets
- Cash-flow requirements
Do not choose an investment simply because it delivered a high return recently.
Give your investments time
Long-term investing works best when you allow your investments sufficient time to grow rather than constantly reacting to short-term market movements.
Read more about The Power of Long-Term Investing.
3. Reduce High-Cost Debt
Debt has a direct impact on net worth because liabilities reduce the value of what you own.
Suppose you have:
- Assets: ₹40 lakh
- Loans and other liabilities: ₹25 lakh
- Net worth: ₹15 lakh
If you reduce your liabilities to ₹20 lakh while keeping your assets unchanged, your net worth rises to ₹20 lakh.
This is why debt repayment can be as important as investing.
High-cost debt deserves particular attention because interest can consume a large part of your future cash flow. Financial education guidance commonly recommends identifying high-interest debt and creating a structured repayment plan.
Use salary increases wisely
When your salary rises, consider directing part of the additional income toward:
Debt repayment + investments + emergency savings
Instead of using every salary increase to upgrade your lifestyle, use some of it to strengthen your balance sheet.
4. Avoid Taking New Debt for Lifestyle Spending
Reducing existing debt is only half the job.
You also need to avoid continuously replacing old debt with new debt.
Buying a car, phone, furniture or expensive lifestyle item on credit may provide immediate satisfaction, but the resulting liability can slow down wealth creation.
Before taking a new loan, ask:
- Do I really need this purchase?
- Can I afford the EMI comfortably?
- Will this debt reduce my ability to invest?
- Will the asset generate income or appreciate?
- What will the purchase cost me including interest?
Not all debt is necessarily bad. A carefully managed home loan, for example, can help you acquire a property that may appreciate and build equity over time. But excessive leverage can work against your financial goals.
5. Build Assets That Can Grow in Value
Your net worth can increase when the value of your assets increases.
Depending on your financial plan, these may include:
- Equity investments
- Mutual funds
- Retirement investments
- Real estate
- Gold
- Business interests
- Other productive assets
However, asset appreciation is never guaranteed.
A property’s value can rise, remain unchanged or fall. Market-linked investments can also experience significant short-term fluctuations.
Real estate can contribute to wealth through a combination of possible appreciation, rental income and increasing equity as a loan is repaid. But property also comes with maintenance costs, taxes, transaction expenses, financing costs and liquidity considerations.
See our detailed guide on Financial Wealth Building Strategy Using Real Estate.
Think beyond purchase price
An asset is not automatically a good wealth-building asset simply because its price may rise.
Consider:
Purchase cost + income generated + expenses + financing cost + potential appreciation
This gives you a more realistic picture of its contribution to your overall wealth.
6. Diversify Your Investments
Increasing net worth does not mean putting all your money into one asset.
Diversification means spreading investments across different assets or investment categories so that your financial position does not depend entirely on one investment. SEBI and Investor.gov both highlight diversification as an important principle of managing investment risk.
For example, a person’s financial assets might include a combination of:
Equity + Debt + Retirement Savings + Gold + Real Estate
The exact mix should depend on individual goals, risk tolerance and time horizon.
Diversification does not eliminate investment risk. Its purpose is to avoid excessive dependence on a single asset or market.
Gold can also play a diversification role for some investors, although it should not automatically be treated as a guaranteed inflation hedge or a complete wealth-building strategy.
For more information, read Financial Wealth Building Strategy Using Physical Gold.
7. Increase Your Income and Invest the Difference
Saving more becomes easier when your income increases.
You can work on increasing income through:
- Better skills
- Career advancement
- Job changes
- Professional qualifications
- Business income
- Freelance work
- Additional income streams
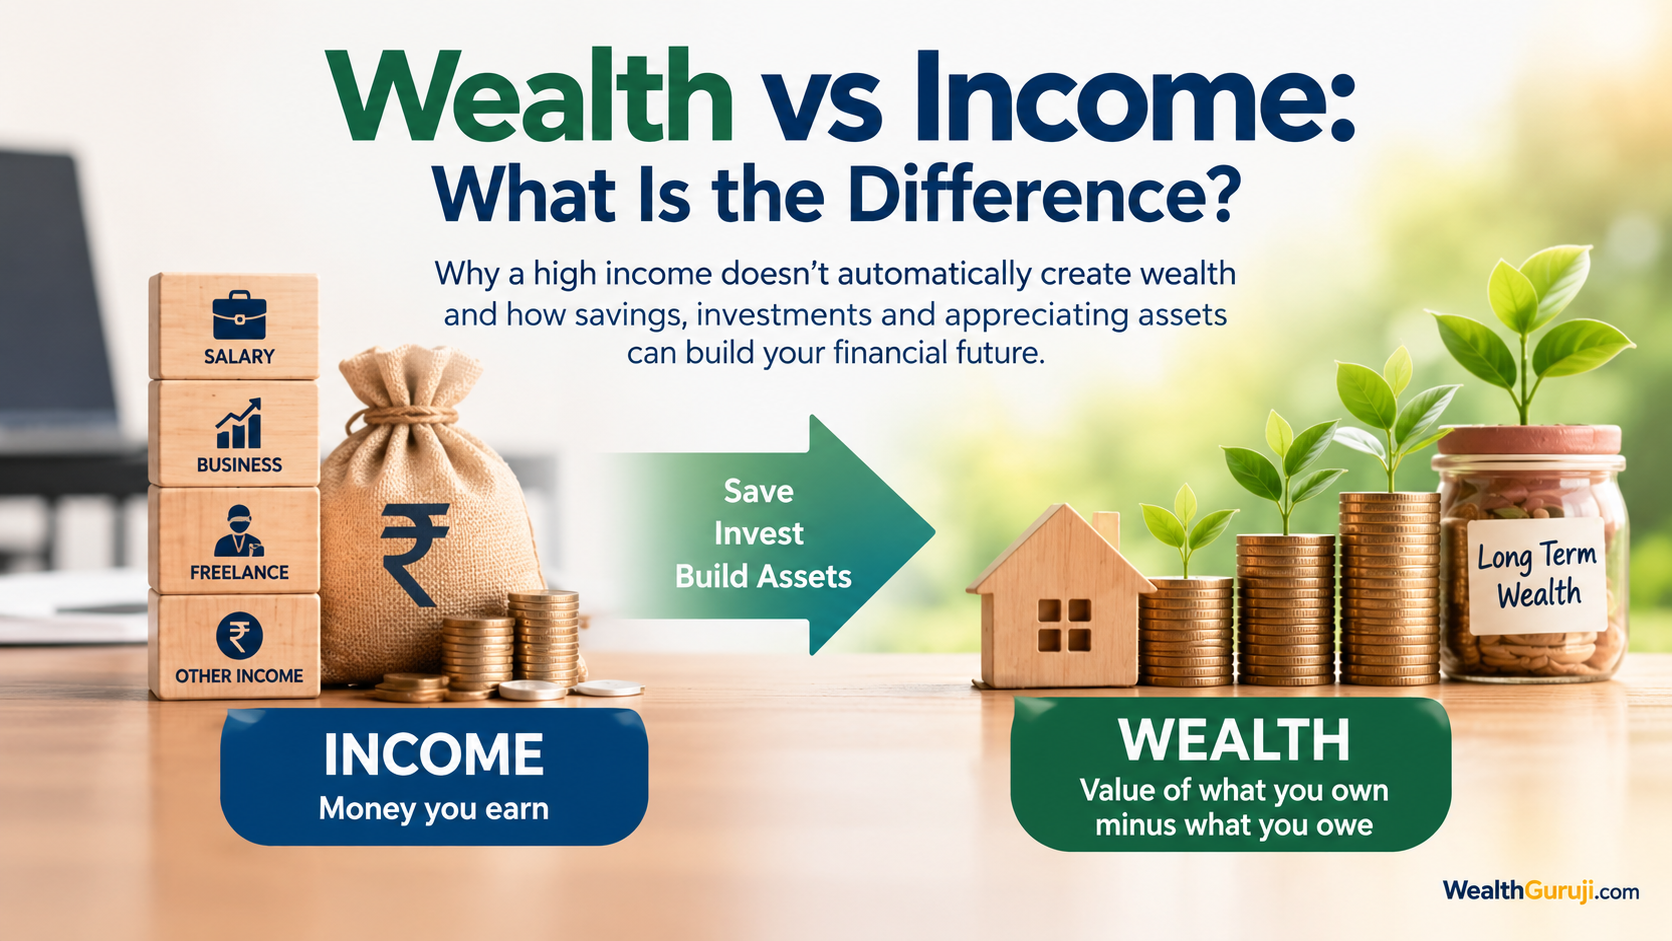
But higher income alone does not create wealth.
A person whose income rises from ₹80,000 to ₹1.2 lakh per month can still have stagnant net worth if spending rises at the same speed.
The real opportunity comes when income increases faster than lifestyle costs.
For example:
Salary increase: ₹20,000
Lifestyle increase: ₹8,000
Additional amount available for wealth building: ₹12,000
That additional ₹12,000 can be divided between investments, debt repayment and cash reserves.
Track Your Net Worth Every Year
You cannot improve what you do not measure.
At least once a year, prepare a simple net-worth statement.
Assets
Add:
- Bank balances
- Fixed deposits
- Mutual funds
- Stocks
- Gold
- Property
- Retirement investments
- Business interests
- Other significant assets
Liabilities
Subtract:
- Home loans
- Personal loans
- Car loans
- Credit card dues
- Education loans
- Other outstanding debts
Then calculate:
Net Worth = Total Assets − Total Liabilities
Tracking this number helps you see whether your financial position is actually improving rather than focusing only on salary or monthly income.
A Simple Example of Annual Net-Worth Growth
Suppose Rahul starts the year with:
Assets: ₹40 lakh
Liabilities: ₹20 lakh
Starting net worth: ₹20 lakh
During the year:
- He saves and invests ₹5 lakh.
- His existing investments and property increase by ₹4 lakh in value.
- He repays ₹2 lakh of loan principal.
At the end of the year:
Assets: ₹49 lakh
Liabilities: ₹18 lakh
Net worth: ₹31 lakh
His net worth has increased by ₹11 lakh.
The important lesson is that the growth did not come from one source. It came from new savings + investment/asset growth + debt reduction.
Actual investment and property values can move up or down, so annual net-worth growth will not always be positive.
Create an Annual Net-Worth Improvement Plan
At the beginning of each financial year, set a few measurable targets.
Target 1: Save More
Decide how much you want to save each month.
Target 2: Invest Consistently
Set a regular investment amount based on your goals and cash flow.
Target 3: Reduce Debt
Set a target for how much loan principal or expensive debt you want to repay.
Target 4: Increase Income
Choose one practical way to improve your earning ability.
Target 5: Review Your Assets
Check whether your investments and other assets still fit your financial objectives.
Target 6: Protect Your Progress
Maintain appropriate insurance and an emergency reserve so that an unexpected financial shock does not force you to sell investments or take expensive debt.
Retirement planning is also an important part of long-term wealth building. PFRDA provides financial education and information on retirement savings options including NPS and APY.
Common Mistakes That Can Slow Down Net-Worth Growth
Lifestyle inflation
Income increases, but expenses increase even faster.
Ignoring debt
A growing investment portfolio may look impressive while expensive debt continues to accumulate.
Chasing quick returns
Trying to make money quickly can lead to taking more risk than your financial situation can support.
Concentrating too much money
Putting most of your wealth into one stock, one property or one asset class can create concentration risk.
Not reviewing your finances
Your income, family responsibilities, goals and liabilities change over time.
Treating every asset as productive
Some assets may have personal value but generate little or no income or appreciation.
A Simple Formula for Growing Net Worth
You can think about annual wealth building in this simple way:
**Higher Income
- Higher Savings
- Regular Investing
- Asset Growth
− Debt
= Higher Net Worth**
The formula is simple, but consistency matters.
You do not need to make perfect financial decisions every year. The bigger objective is to make your financial position stronger over time.
Key Takeaways
- Increase your savings gradually whenever your income rises.
- Invest regularly and give long-term investments enough time to compound.
- Reduce high-cost debt and avoid unnecessary new borrowing.
- Build diversified assets that can potentially grow in value.
- Increase your income and direct part of every income increase toward wealth creation.
- Review your net worth at least annually.
- Do not depend on asset appreciation alone; combine savings, investing and debt management.
- Focus on your long-term financial trend, not one good or bad year.
Conclusion
Increasing your net worth every year is less about finding the perfect investment and more about building a strong financial system.
Earn more. Spend with intention. Save consistently. Invest for the long term. Reduce unnecessary debt. Build a diversified asset base. Protect what you have already accumulated.
Some years may produce faster progress than others. Investment markets may fall, property values may stagnate and unexpected expenses may temporarily reduce your net worth.
That is normal.
The real objective is to keep improving your financial position over a long period.
When your assets gradually increase, your liabilities are brought under control and your savings are put to productive use, your net worth has a stronger foundation for long-term growth.
Frequently Asked Questions
How can I increase my net worth quickly?
There is no reliable shortcut to building wealth. The most practical approach is to increase savings, grow income, invest regularly and reduce expensive debt while avoiding unnecessary financial risks.
What should I focus on first: saving, investing or paying debt?
It depends on your situation. Build adequate emergency savings, then give priority to expensive debt while continuing appropriate long-term investing. The right balance depends on interest costs, cash-flow stability and financial goals.
Can increasing my salary increase my net worth?
Yes, but only when part of the additional income is retained and directed toward savings, investments or debt repayment. If lifestyle expenses increase by the same amount as income, the impact on net worth may be limited.
Does property appreciation increase net worth?
Yes. If the market value of a property increases and your liabilities remain unchanged, your net worth can increase. However, property values are not guaranteed to rise and transaction, maintenance and financing costs should also be considered.
Is SIP good for increasing net worth?
A SIP is a method of investing a fixed amount regularly in a mutual fund scheme. It can help investors develop investment discipline and participate in long-term market growth, but mutual fund investments carry market risk and returns are not guaranteed.
How often should I calculate my net worth?
For many people, a detailed review once or twice a year is sufficient. The important thing is consistency. Comparing your current net worth with previous years can help you identify whether your financial position is improving.