10 Habits That Help Build Long-Term Wealth
Building wealth is usually not about finding one perfect investment or making a quick financial gain. For most people, long-term wealth grows through small financial decisions repeated consistently over many years.
Your income matters, but what you do with that income matters just as much. Saving regularly, investing with discipline, controlling lifestyle inflation, managing debt and reviewing your finances can gradually strengthen your financial position.
This article explains 10 practical habits that help build long-term wealth, especially for salaried professionals, young earners and families in India. The goal is not to promise quick wealth, but to develop financial habits that can support wealth accumulation over time.
What Does Long-Term Wealth Building Mean?
Long-term wealth building is the gradual process of increasing your financial assets while keeping unnecessary liabilities under control.
A simple way to look at it is:
Earn → Save → Invest → Grow → Protect → Review
Income provides the starting point. Savings create a financial cushion. Investments can help your money grow over time, while debt management and insurance can protect your progress.
SEBI’s investor education material highlights the importance of starting early, investing regularly, understanding risk, maintaining diversification and focusing on long-term financial goals. It also stresses that investments involve risk and do not provide guaranteed returns.
For a broader introduction, read our guide on What Is Wealth Building and How Does It Work?.
10 Habits That Help Build Long-Term Wealth
1. Save Before You Spend
One of the simplest wealth-building habits is to save part of your income before discretionary spending begins.
Many people follow this pattern:
Income → Expenses → Whatever is left goes to savings
A more useful approach is:
Income → Savings and Investments → Expenses
This does not mean sacrificing every enjoyable expense. It means giving long-term financial goals a place in your monthly budget before lifestyle spending absorbs the available cash.
How to make this habit practical
Set an automatic transfer immediately after your salary arrives. The amount can start small and increase gradually as your income grows.
For example, someone earning ₹80,000 a month might decide to automatically direct ₹10,000–₹15,000 toward long-term financial goals and then manage regular expenses from the remaining amount.
The exact percentage should depend on income, family responsibilities, debt and financial goals rather than following a fixed rule blindly.
2. Invest Regularly Instead of Waiting for the “Perfect” Time
Regular investing can be more practical than waiting for the perfect market entry point.
A SIP is one example of this approach. AMFI describes a Systematic Investment Plan as a method of investing a fixed amount in a mutual fund scheme at regular intervals. Regular investing can encourage discipline and reduce the temptation to make every investment decision based on short-term market movements.
Investor.gov similarly explains that investing equal amounts at regular intervals can help investors maintain a consistent investment pattern despite market ups and downs.
However, regular investing does not eliminate investment risk.
A practical habit
Choose investments based on your:
- Financial goal
- Investment time horizon
- Risk tolerance
- Asset allocation
- Need for liquidity
Then automate the contribution where appropriate.
The objective is not to predict every market movement. It is to develop a repeatable investment habit.
3. Control Lifestyle Inflation When Your Income Rises
A salary increase can improve your financial life, but it can also increase expenses just as quickly.
This is known as lifestyle inflation: as income rises, spending on housing, cars, dining, travel, subscriptions and other wants also increases.
Suppose your salary increases by ₹15,000 a month. You could spend the entire increase, or divide it between higher investing, debt repayment, future goals and lifestyle improvements.
A useful habit is to allow yourself some lifestyle improvement while directing a meaningful portion of every increment toward wealth creation.
Try the “salary raise rule”
Whenever your income increases:
Increase investments first, improve lifestyle second.
For example:
| Salary increase | Possible use |
|---|---|
| ₹15,000 | ₹7,000 additional investment |
| ₹3,000 debt repayment | |
| ₹2,000 future goal | |
| ₹3,000 lifestyle improvement |
This is only an illustration. The actual split should match your circumstances.
The important habit is to ensure that your savings and investments rise along with your income.
4. Build an Emergency Fund Before Taking More Investment Risk
Long-term investments are not a substitute for emergency savings.
An emergency fund can help deal with situations such as job loss, unexpected medical expenses, major repairs or sudden family obligations without immediately selling investments or relying heavily on expensive credit.
SEBI’s investor education guidance specifically recommends maintaining an emergency fund before investing, while the CFPB notes that emergency savings can help households deal with unexpected financial shocks and reduce dependence on credit or retirement savings when emergencies occur.
How to build the habit
Start with a realistic target based on your essential monthly expenses.
Keep emergency money in relatively accessible and low-risk forms rather than investing the entire reserve in volatile assets.
For example, if essential monthly expenses are ₹40,000, a person may gradually build a cash reserve rather than trying to create the entire fund in one month.
The right amount depends on job stability, family responsibilities, insurance coverage, debt and income variability.
5. Pay Down Expensive Debt and Borrow Carefully
Debt can either support a financial goal or weaken your ability to build wealth.
A home loan used to purchase a suitable property is financially different from repeatedly using high-cost credit for lifestyle expenses.
The RBI’s financial-awareness material encourages responsible borrowing, evaluating repayment ability and using regulated lending institutions. It also emphasizes timely repayment and maintaining responsible credit behaviour.
Make debt management a regular habit
Review:
- Outstanding loan balances
- Interest rates
- Remaining tenure
- Monthly EMIs
- Credit-card dues
- Total interest cost
High-cost debt deserves particular attention because interest charges can compete directly with your ability to save and invest.
A simple monthly rule can be:
Do not take new debt without understanding how it affects future cash flow.
6. Use EPF and Other Retirement Savings Consistently
Retirement planning should not be postponed until the final years of employment.
For eligible salaried employees, EPF can form an important part of long-term retirement savings. EPFO describes the Employees’ Provident Fund as a statutory benefit, with accumulated contributions and interest providing benefits at retirement or on exit subject to applicable rules.
Other retirement-oriented options may also be relevant depending on the individual’s circumstances, such as NPS or PPF.
PFRDA describes NPS as a defined-contribution pension system designed to encourage systematic and regular savings during working years for retirement income.
Turn retirement saving into a habit
Whenever your income increases, review whether your retirement contribution should also increase.
The key is consistency. Retirement wealth is generally built over long periods rather than through occasional large investments.
Our guide on Increase Retirement Wealth Through Higher EPF Contributions explains how higher retirement contributions can fit into a broader wealth-building strategy.
7. Set Specific Financial Goals
“Become wealthy” is too vague to guide monthly decisions.
Instead, convert broad ambitions into measurable goals.
For example:
| Goal | Target | Time Horizon |
|---|---|---|
| Emergency fund | ₹3 lakh | 18 months |
| Home down payment | ₹15 lakh | 5 years |
| Child’s education | ₹25 lakh | 10 years |
| Retirement corpus | Goal-specific | 20+ years |
A goal becomes much easier to manage when you know:
Goal → Amount Required → Target Date → Monthly Contribution
SEBI recommends considering your financial goals, investment horizon and risk appetite before choosing investments.
This also prevents a common mistake: investing in an unsuitable product simply because it has recently performed well.
8. Diversify Instead of Depending on One Asset
Putting most of your wealth into one investment, company, asset class or property can increase concentration risk.
Diversification means spreading investments across different assets so that your financial position is not dependent on the performance of one holding.
SEBI and Investor.gov both emphasize diversification and appropriate asset allocation as important ways to manage investment risk. Diversification cannot prevent all losses, but it can reduce the impact of poor performance in a single investment.
Diversification does not mean owning everything
A diversified portfolio is not necessarily one containing dozens of products.
The aim is to create an asset mix appropriate for:
- Your goals
- Your time horizon
- Your risk tolerance
- Your liquidity needs
For example, someone saving for a goal due next year should generally think differently about risk than someone investing for retirement several decades away.
SEBI recommends reviewing investments and rebalancing when circumstances or the intended asset mix change.
9. Protect Wealth With Insurance and Risk Management
Building wealth is only one side of financial planning. Protecting the wealth you already have is equally important.
A major medical event, disability, loss of income or death of an earning family member can seriously affect a household’s finances.
IRDAI explains that health insurance provides financial protection by reimbursing eligible medical expenses according to the policy terms. It also advises policyholders to understand coverage, exclusions, waiting periods, deductibles and other conditions.
Make protection part of your annual financial review
Review whether you have appropriate:
- Health insurance
- Life insurance where dependants need income protection
- Personal accident protection where relevant
- Emergency savings
- Updated nominations
Insurance should be selected based on financial risk and family requirements, not simply because a product is being marketed.
The goal is simple:
Do not allow one unexpected event to undo years of wealth building.
10. Review Your Finances and Net Worth Every Year
One of the most overlooked wealth-building habits is reviewing your financial position regularly.
You do not need to track your investments every day.
Instead, schedule a financial review once or twice a year.
Check:
- Income and expenses
- Savings rate
- Emergency fund
- Outstanding debt
- Investment allocation
- EPF and retirement savings
- Insurance coverage
- Financial goals
- Net worth
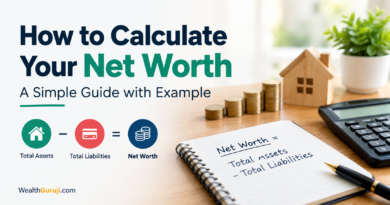
Your net worth can be calculated as:
Net Worth = Total Assets − Total Liabilities
For example:
| Financial position | Amount |
|---|---|
| Investments and savings | ₹15 lakh |
| Property and other assets | ₹35 lakh |
| Total assets | ₹50 lakh |
| Home and other loans | ₹18 lakh |
| Net worth | ₹32 lakh |
Tracking the trend over several years can tell you much more about wealth accumulation than looking only at your salary.
Read our detailed guide on How to Calculate Your Net Worth.
You can also read Wealth vs Income: What Is the Difference? to understand why a high income and high wealth are not necessarily the same thing.
A Simple Monthly Wealth-Building Routine
You do not have to overhaul your entire financial life at once.
A simple monthly routine can look like this:
Salary received
↓
Essential expenses and bills
↓
Emergency savings, if still being built
↓
Automatic investments and retirement contributions
↓
Debt repayment
↓
Discretionary spending
↓
Monthly financial check
Then, once or twice a year, perform a bigger review of your goals, investments, insurance and net worth.
This approach makes wealth building a system rather than a one-time decision.
What If You Cannot Save a Large Amount?
Do not assume that wealth building is only for high-income households.
The amount available for saving may be small at the beginning of your career. That does not make the habit meaningless.
A person who starts with ₹2,000 per month can focus first on consistency. As income rises, the contribution can gradually increase.
The important progression is:
Start → Stay consistent → Increase contributions → Review → Continue
SEBI’s investor education resources emphasize that starting early and investing regularly can provide more time for compounding to work. At the same time, investment returns are not guaranteed, so wealth-building plans should be based on realistic assumptions rather than promises of fixed returns.
Common Mistakes That Can Slow Down Wealth Building
Even good financial habits can be weakened by a few common mistakes.
Chasing quick returns
Trying to become wealthy quickly can lead to excessive risk and unsuitable investments.
Increasing expenses every time income rises
A higher salary does not automatically create higher wealth.
Ignoring debt
High-cost debt can quietly consume cash flow that could otherwise be invested.
Investing without an emergency fund
This can force you to sell long-term investments when an unexpected expense occurs.
Checking investments too frequently
Long-term investing requires patience. Constantly reacting to short-term market movements can undermine a well-designed financial plan.
Ignoring insurance
A large financial shock can undo years of savings and investments.
Never reviewing the plan
Your salary, family responsibilities, goals and risk capacity change over time. Your financial plan should change when necessary.
Key Takeaways
The most useful habits for building long-term wealth are not complicated:
- Save before you spend.
- Invest regularly and stay focused on the long term.
- Control lifestyle inflation as your income rises.
- Build an emergency fund.
- Manage expensive debt carefully.
- Use EPF and other retirement savings consistently.
- Set specific financial goals.
- Diversify and match investments to your risk and time horizon.
- Protect your finances with suitable insurance.
- Review your net worth and financial plan regularly.
The common thread is consistency.
You do not need to make perfect financial decisions every month. You need a system that helps you make sensible decisions repeatedly for many years.
Conclusion
Long-term wealth is usually built gradually.
There may be no dramatic moment when wealth suddenly appears. Instead, years of saving, investing, debt management, disciplined spending and asset accumulation can gradually improve your financial position.
The most important habit is to turn wealth building into a regular part of your financial life.
Start with the habits you can control today. Save consistently, invest according to your goals and risk tolerance, avoid unnecessary debt, protect your family and review your progress.
Over time, these ordinary financial habits can become the foundation for stronger long-term wealth.
Frequently Asked Questions
1. What are the best habits for building long-term wealth?
Important habits include saving regularly, investing consistently, controlling lifestyle inflation, managing debt, maintaining an emergency fund, protecting against major financial risks and reviewing net worth periodically.
2. How much of my income should I save?
There is no single percentage that works for everyone. Your savings target should consider your income, essential expenses, debt, family responsibilities, emergency fund and financial goals. Start with an amount you can maintain consistently and increase it as your income grows.
3. Is SIP a good habit for long-term wealth building?
A SIP is a method of investing a fixed amount at regular intervals in a mutual fund scheme. It can encourage investment discipline, but mutual fund investments are subject to market risk and a SIP does not guarantee returns.
4. How does lifestyle inflation affect wealth building?
Lifestyle inflation happens when spending rises along with income. When most salary increases are consumed by higher expenses, less money is available for savings, investments and debt reduction.
5. Should I invest or repay debt first?
It depends on the type and cost of debt, your financial goals, emergency savings and investment risk. High-cost debt generally deserves serious attention before taking additional investment risk. RBI’s financial-awareness guidance emphasizes responsible borrowing and assessing repayment capacity.
6. Is EPF useful for long-term wealth building?
For eligible employees, EPF can be an important long-term retirement savings component. EPFO states that EPF provides accumulated savings plus applicable interest as a retirement or exit benefit subject to the scheme’s rules.
7. How often should I review my financial plan?
A detailed review once or twice a year is reasonable for many people. You should also review your plan after major life events such as marriage, childbirth, a major salary change, buying a home or changing jobs.
8. Can I build wealth on a modest salary?
Yes. Wealth building does not depend only on having a high income. Consistent saving, controlled expenses, appropriate investing and gradual increases in contributions can help improve your financial position over time.
Disclaimer
This article is provided for general educational and informational purposes only. It is not personalised investment, tax, legal or financial advice. Investment products involve different levels of risk, and past performance does not guarantee future results. Before making financial decisions, consider your own goals, financial situation, risk tolerance and applicable rules, and consult a qualified professional where appropriate.